
For families searching for “financial advisor Longmont,” the central question is not simply where to invest. It is how to coordinate a balance sheet shaped by Longmont real estate, Colorado taxes, Front Range employment, commuting costs, retirement objectives, and concentrated exposure to the local economy.
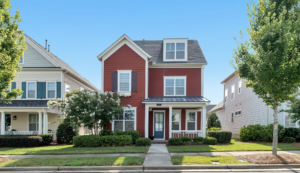
Longmont has become a compelling alternative to Boulder for households seeking more home for the money. The median single-family home price was approximately $624,500 as of August 2026-roughly half of Boulder’s median. That difference can create meaningful planning capacity, but only if the resulting cash flow and equity are deliberately integrated into a broader wealth strategy.
The St. Vrain Valley is also evolving. Longmont’s agricultural and manufacturing roots now intersect with technology, aerospace, bioscience, photonics, advanced manufacturing, and AI-related infrastructure. BizWest’s regional reporting highlights the area’s growing economic sophistication. For many households, that creates higher earning potential, equity compensation, and career opportunity, but also greater concentration risk.
What a financial advisor Longmont household should assess
A capable financial advisor Longmont families can work with should evaluate the complete relationship between income, assets, liabilities, taxes, and future decisions. Investment performance is only one component.
A comprehensive review should address:
- Investment management: Asset allocation, diversification, tax-efficient implementation, liquidity, and risk capacity.
- Tax strategy: Colorado income tax, federal tax exposure, Roth conversion opportunities, capital gains, charitable giving, and equity compensation.
- Cash flow: Monthly spending, savings rates, mortgage obligations, property taxes, commuting expenses, and investment-generated cash flow.
- Retirement readiness: Retirement income, Social Security timing, healthcare costs, housing decisions, and withdrawal sequencing.
- Estate planning: Beneficiary designations, trusts, powers of attorney, charitable objectives, and the orderly transfer of wealth.
- Risk management: Life, disability, liability, property, umbrella, and long-term-care coverage.
This integrated view is especially important when a household owns a valuable residence, receives stock from a local employer, and expects income to rise through a specialized career. Each decision affects the others. A home purchase can change investment capacity. Employer stock can increase both wealth and portfolio concentration. A future retirement move can generate taxable gains and alter cash-flow requirements.
The direct benefit is coordination: fewer isolated decisions and greater control over how each dollar supports the household’s objectives.

The “Boulder premium” and Longmont real estate
The price difference between Boulder and Longmont creates what can be described as a “Boulder premium” arbitrage. Some households sell a higher-priced Boulder property and move to Longmont. Others choose Longmont initially, preserving capital that would otherwise have been committed to a more expensive home.
That difference can be directed toward:
- Taxable investment accounts.
- Roth and traditional retirement contributions.
- Emergency and opportunity reserves.
- Education funding.
- Debt reduction.
- Business ownership or other long-term investments.
- A higher sustainable retirement spending level.
The critical issue is not simply that Longmont real estate may cost less. The issue is what the household does with the capital that remains available after purchasing the home.
A home is also a concentrated, illiquid asset. It can provide stability and long-term appreciation, but it does not automatically produce spendable retirement income. A financial advisor Longmont relationship should therefore distinguish between:
- Net home equity.
- Investable assets.
- Cash flow generated by the portfolio.
- Liquidity available for unexpected needs.
- The household’s willingness to sell, borrow, or downsize later.
A household that owns a $1 million home but has limited liquid investments may be less financially flexible than a household with a less expensive home and a diversified portfolio. Comprehensive financial planning makes that trade-off visible.
The real cost of a Front Range commute
Longmont residents may commute to Boulder, Broomfield, Denver, or other employment centers. The financial cost extends well beyond gasoline.
A realistic commute analysis should include:
- Fuel and electricity.
- Vehicle maintenance and tires.
- Depreciation and replacement timing.
- Insurance and registration.
- Parking, tolls, and public transportation.
- Work-related meals and incidental expenses.
- Time spent commuting and the effect on family capacity.
- The financial value of remote or hybrid work flexibility.
Time is a financial planning variable. A longer commute can affect childcare, household services, health routines, professional development, and the ability to pursue additional income. It can also influence whether a household remains in Longmont, moves closer to work, or accepts a higher housing cost in exchange for reduced travel.
The right financial advisor Longmont households choose should model these alternatives rather than treat commuting as an unexamined lifestyle expense. A relocation decision should compare after-tax income, housing costs, property taxes, transportation expenses, expected investment savings, and the value of recovered time.
The outcome is a more accurate cash-flow plan. That improves the household’s ability to save, invest, and make location decisions without relying on broad assumptions.
Property taxes under Boulder County rules
Property taxes require particular attention because the calculation is more complex than applying one rate to a home’s market value.
For 2026, Boulder County identifies separate residential assessment treatment for school districts and other local taxing entities:
- A 7.05% assessment rate applies to the school district portion.
- A 6.8% assessment rate applies to other local governments.
- For the local-government portion, a 10% reduction applies to the first $700,000 of actual value, subject to the county’s calculation rules.
- Longmont’s combined mill levy varies by parcel and taxing district, with a typical total near 80 mills.
- Effective property tax rates commonly fall in an approximate range of 0.47% to 0.55% of actual market value, depending on the property and overlapping districts.
The Boulder County Assessor’s tax calculation page provides the applicable formulas and explains how assessed value and mill levies interact. The county’s mill levy information should be reviewed for the specific parcel.
A $624,500 home, for example, should not be modeled using a simplistic market value multiplied by a single assumed tax rate. The correct calculation depends on the school and local-government portions, applicable adjustments, and the property’s taxing districts.
Property tax planning should be incorporated into:
- Mortgage and escrow projections.
- Retirement housing budgets.
- Rental property analysis.
- Long-term cash-flow forecasts.
- Downsizing and relocation comparisons.

Why Colorado tax planning matters
Colorado’s baseline individual income tax rate is 4.4% for the 2025 tax year under current Department of Revenue guidance. TABOR can affect temporary rate reductions and refund mechanisms, but those benefits should not be treated as permanent planning assumptions.
The Colorado Department of Revenue’s individual income tax guidance and TABOR resources should be consulted for current rules.
For a Longmont household, state tax planning may involve:
- Choosing between traditional and Roth retirement contributions.
- Evaluating Roth conversions before required minimum distributions.
- Managing capital gains and qualified dividends.
- Coordinating charitable gifts with appreciated securities.
- Reviewing equity compensation withholding and estimated payments.
- Planning the tax impact of selling a business or investment property.
- Coordinating federal and Colorado tax consequences during retirement.
IRS rules also matter. Traditional IRA and most 401(k) distributions are generally taxable as ordinary income, while qualified Roth distributions can receive different treatment. The IRS guidance on IRA distributions and required minimum distributions provide the governing framework.
A financial advisor Longmont household engages should coordinate tax projections with investment and retirement decisions. The direct benefit is efficiency: the household retains more of its resources while avoiding preventable tax surprises.
Retirement downsizing in the St. Vrain Valley
Longmont’s relative housing affordability can change the calculus for retirement. A household may be able to sell a larger home, purchase a smaller property in the same region, and release equity for retirement income or portfolio diversification.
That decision requires more than comparing sale price and purchase price. Planning should account for:
- Selling costs and possible capital gains.
- Moving and renovation expenses.
- Property taxes on the replacement home.
- Home maintenance and insurance.
- Healthcare access and transportation.
- Proximity to family and community.
- The amount of equity converted into investable assets.
- Whether the new property remains suitable as mobility and care needs change.
Downsizing can strengthen retirement readiness, but it can also fail to deliver its expected benefit if the replacement home is expensive, transaction costs are underestimated, or released equity is not invested according to a disciplined withdrawal plan.

Manage regional concentration risk
Longmont’s economic growth creates opportunity, but local prosperity can also produce correlated risk. A household may simultaneously own:
- Longmont residential real estate.
- Employer stock from a local technology, aerospace, bioscience, or manufacturing company.
- Human capital tied to the same regional economy.
- A business serving local employers or residents.
These exposures can decline together during a regional employment contraction, industry downturn, or housing correction. Employer stock should therefore be evaluated not only as an investment, but as an extension of the household’s income and geographic risk.
Questions to examine include:
- What percentage of net worth is tied to one employer?
- Are stock awards being sold or retained without a written policy?
- Would a job loss and stock decline occur at the same time?
- Is the investment portfolio diversified away from the local economy?
- Does the household have sufficient liquidity for a prolonged transition?
A prospective financial advisor Longmont family members interview should be able to explain how concentration risk will be measured, monitored, and reduced over time.
Questions to ask a prospective fiduciary advisor
Before engaging an advisor, ask:
- Are you a Registered Investment Advisor, and when does your fiduciary duty apply?
- Are your recommendations limited to investments, or do they integrate taxes, cash flow, retirement, estate planning, and risk?
- How do you evaluate employer stock and other concentrated positions?
- Can you model Longmont housing, property taxes, commuting, and retirement relocation decisions?
- How are you compensated, and what additional costs should clients expect?
- Which CFP® professionals will participate in the relationship?
- How frequently will the plan be reviewed and updated?
- How do you distinguish a sustainable withdrawal strategy from a simple portfolio allocation?
InSight Financial Planners applies its proprietary InSight-Full® planning process to coordinate the six core planning elements around the client’s goals. The firm’s CFP® professionals integrate investment management, tax strategy, cash flow, retirement, estate planning, and risk management into an ongoing advisory relationship.
For a financial advisor Longmont search, the relevant standard is not proximity alone. It is the ability to connect local realities to a disciplined, long-term financial plan.
Conclusion
Growing wealth in Longmont requires more than selecting investments or monitoring home values. It requires deliberate coordination of real estate, taxes, commuting, employment, retirement income, estate objectives, and portfolio risk.
The right financial advisor Longmont households select should help convert the region’s opportunities into measurable financial progress while identifying the risks created by concentration, illiquidity, and tax complexity. InSight’s client-centered approach is designed to provide that coordination through ongoing financial planning, investment management, and financial coaching.
The result is greater stability, control, and efficiency across the household’s financial life.
Meta description: Learn how Longmont households can coordinate real estate, Colorado taxes, commuting, retirement, and employer stock through comprehensive financial planning.
Category: Articles and News
Tags: a financial advisor · comprehensive financial planning · financial coaching for families · Retirement Readiness · Real Estate · Tax Strategy · Complex Wealth Problems
Disclosure: This article is provided for informational and educational purposes only and does not constitute individualized investment, tax, legal, or financial advice. Tax laws, property-tax rules, market conditions, and individual circumstances change over time. Consult qualified tax and legal professionals regarding your specific situation. Investment advisory services are offered through InSight Financial Planners, a Registered Investment Advisor. Past performance is not indicative of future results.